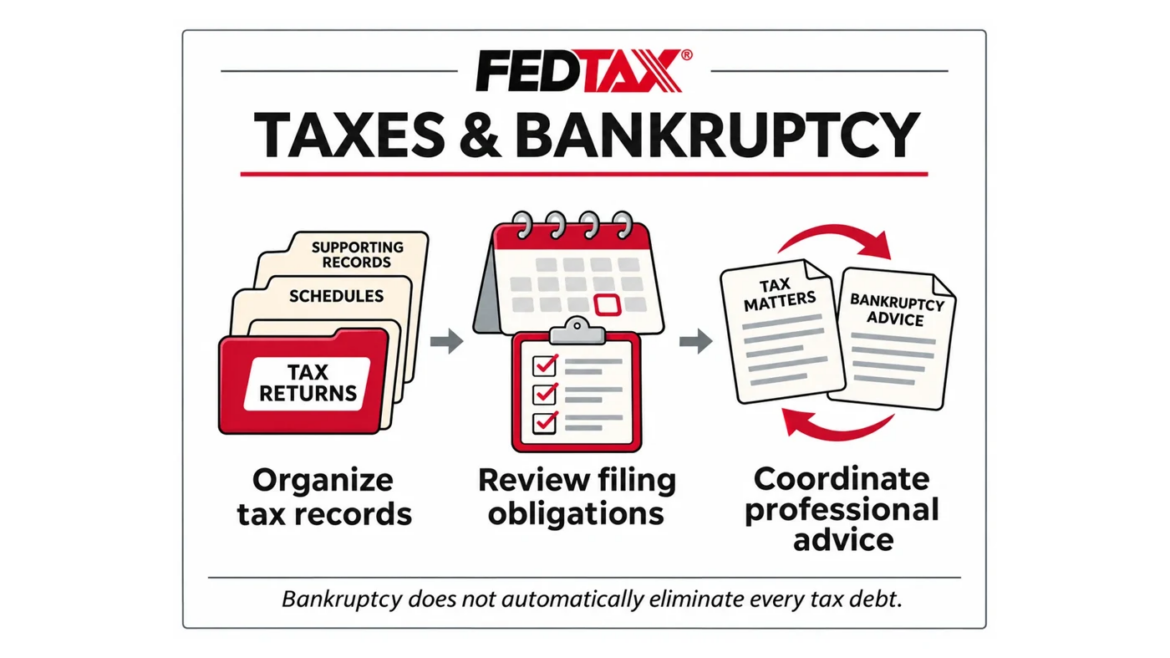
Bankruptcy and tax filing involve overlapping responsibilities. Tell your tax preparer about a pending or active bankruptcy case, and coordinate decisions with your bankruptcy attorney and trustee. A general article cannot determine how a particular tax debt, refund, or asset will be treated.
The bankruptcy chapter matters
For an individual Chapter 7 or Chapter 11 case, a separate taxable bankruptcy estate generally exists. The trustee or debtor-in-possession handles the estate’s filing responsibilities, including Form 1041 when required. The individual continues to have personal return obligations.
Individual Chapter 12 and Chapter 13 cases do not create a separate taxable estate for federal income-tax purposes. The debtor generally continues filing an individual return. Required filings and deadlines should be reviewed for the specific case.
Review refunds and payments before acting
Do not use a generic rule to decide whether to spend a refund, pay a creditor, transfer assets, or delay a return. Discuss those actions with your bankruptcy attorney. Ask your tax preparer what information is needed to prepare accurate returns and coordinate with the legal team.
Bring these records
- The bankruptcy chapter, filing date, and attorney contact information.
- Prior returns and a list of any unfiled years.
- Tax notices, account records, and payment history.
- Income documents and any cancellation-of-debt forms.
- Trustee requests and court-related filing deadlines.
FEDTAX® can discuss your tax preparation needs and unfiled returns. Describe the bankruptcy case when you request a consultation so the appropriate scope and coordination can be discussed. Bankruptcy legal strategy should be addressed with your bankruptcy attorney.
Official reference: IRS Publication 908, Bankruptcy Tax Guide.